
Investment Leverage - Using Capital to Build Sustainable Wealth
How borrowed capital can magnify returns — and risks — and why leverage should serve a disciplined investment strategy, not replace one.

By Junah Mpofu
More than 33 years in banking, including mortgage and credit lending, and a real estate portfolio of her own
Read to the end to earn a 20 gold points reward.
What is the Gold Points Reward (GPR)?
GPR is our points reward system. As the Junahyeng Academy platform grows, it lets you earn points and rewards: the more points you earn, the higher the rewards you will unlock in due course.
You earn points for reading and engaging with our guides and articles. Soon you will also earn them for referring friends to the platform, engaging with our socials, and more.
Create a free account to keep the points you earn.
Introduction
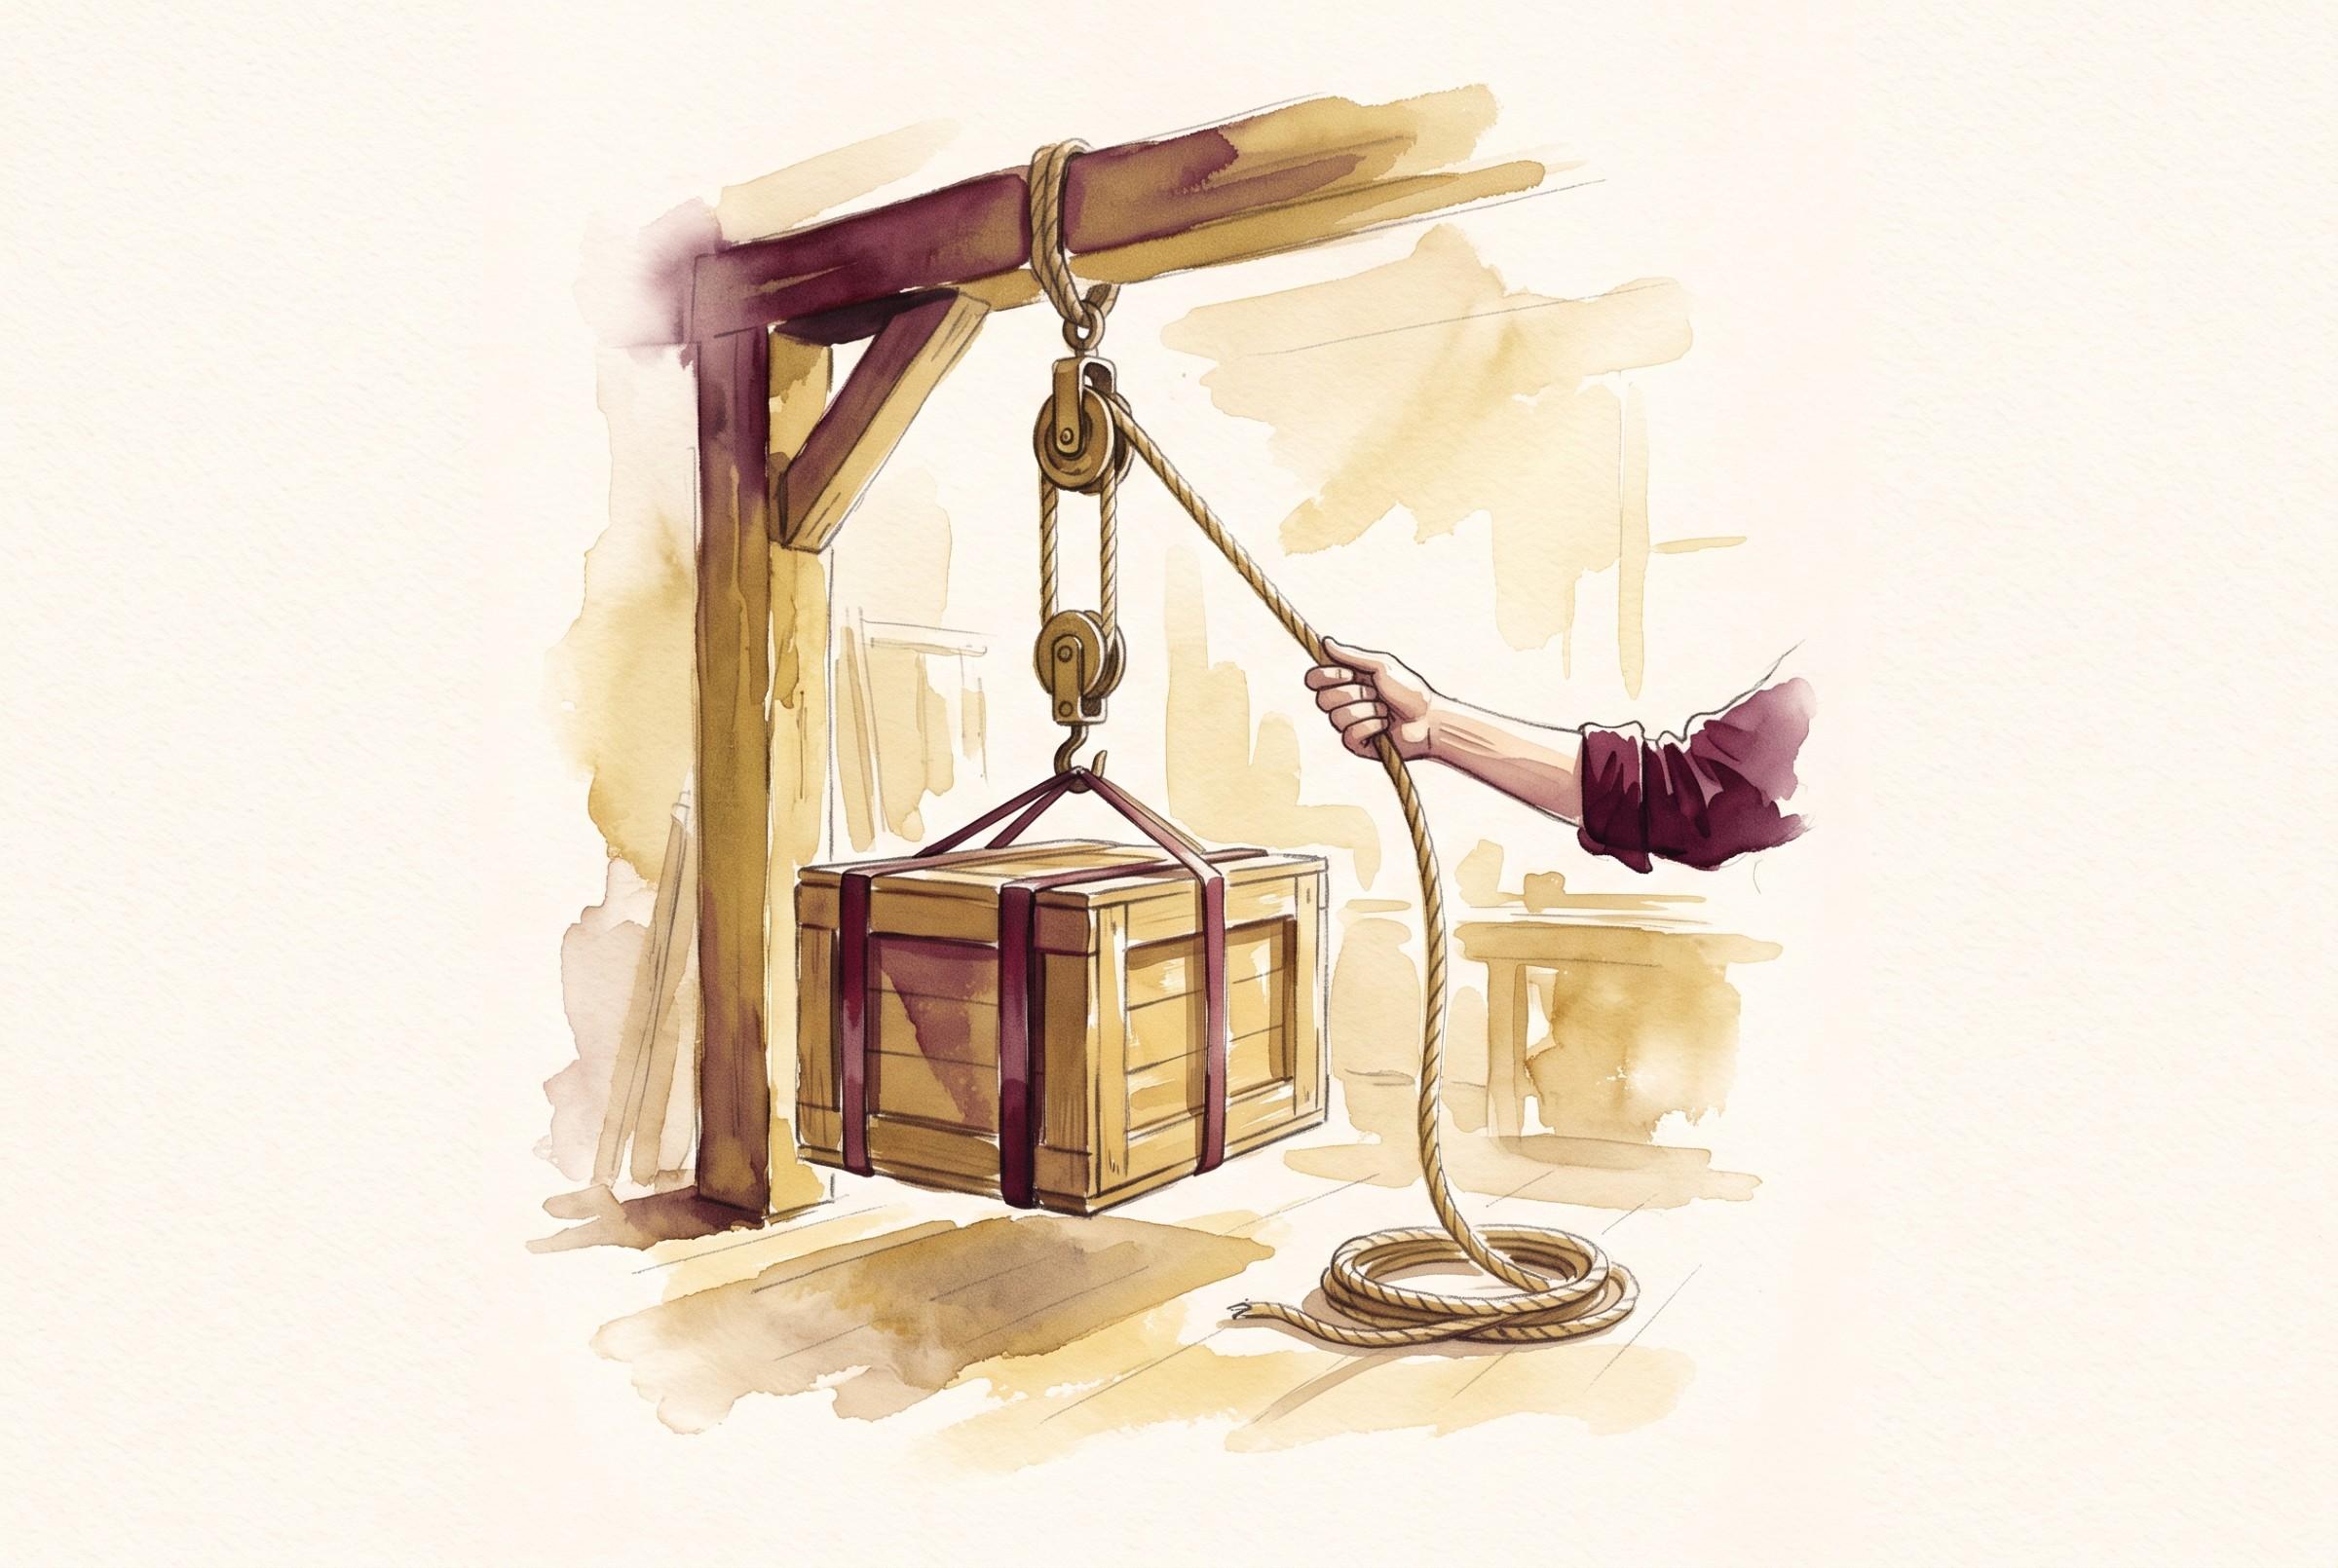
Investment leverage is one of the more powerful—and more misunderstood—tools in wealth building. At its simplest, leverage means using borrowed capital or other financial resources to increase the amount available for an investment. The appeal is clear: by controlling a larger productive asset with a smaller amount of personal capital, an investor may increase the potential return on their own money. However, leverage works in both directions. It can magnify opportunity, but it can also magnify losses. For that reason, leverage should never be presented as a shortcut to wealth. It is a financial tool that requires knowledge, discipline, reliable cash flow, and careful risk assessment.
What Investment Leverage Means
Leverage allows an investor to pursue an investment larger than what their own capital alone could purchase. This is commonly done through financing, where the investor contributes part of the capital and borrows the remainder. When used responsibly, leverage can help investors expand ownership of productive assets—such as income-generating property, a business interest, or other appreciating investments. When used carelessly, it can expose the investor to financial strain and losses that exceed their original expectations.
An Illustrative Example
Imagine an investor who has $50,000 of their own capital. Instead of purchasing a $50,000 asset outright, the investor may use that amount as part of the financing for a larger investment. If the investment generates sufficient income and appreciates in value, the investor may benefit from controlling a larger asset than their original capital could have acquired alone. However, the borrowed portion must still be serviced.
If the investment declines in value or fails to generate the expected income, the investor may face losses while remaining responsible for the debt. This is the central principle of leverage: it magnifies both opportunity and risk.
Investment Leverage Is Not Consumption Debt
It is important to distinguish investment leverage from borrowing for consumption. Debt used to buy items that quickly lose value and produce no income can create financial pressure without building long-term wealth. Investment leverage, when appropriately structured, is intended to acquire or expand ownership of an asset with the potential to generate income, appreciate, or both. The purpose of the borrowing therefore matters. Consumption debt often takes from future income. Strategic investment leverage attempts to use capital to build future value.
The Role of Cash Flow
Cash flow is one of the most important considerations in leveraged investing. An investment may appear attractive on paper, but if the investor cannot comfortably meet the debt obligations, the structure can become dangerous. Before using leverage, an investor should understand the following:
- Expected income from the investment
- Financing costs and interest rates
- Repayment obligations
- Taxes, insurance, and other expenses
- Vacancy periods or periods without income, where applicable
- Maintenance and operating costs
- Market risk and valuation changes
- Interest-rate risk
- Liquidity risk
- The investor’s ability to withstand unexpected losses
The objective is not simply to make the numbers work under ideal conditions. A responsible investor also asks what happens if conditions change, income is delayed, costs rise, or the market moves against the investment.
The Importance of a Margin of Safety
The strongest investment strategy is not always the one that produces the highest projected return. Often, the stronger strategy is the one that provides enough financial breathing room to survive unexpected circumstances. A margin of safety helps protect an investor from being forced into poor decisions because of temporary financial pressure. This may include maintaining reserves, using conservative projections, avoiding excessive debt, and ensuring that the investment can withstand stress.
Knowledge Before Leverage
Investment leverage should come after financial literacy—not before it. Before borrowing to acquire an asset, an investor should understand:
- The underlying asset and how it creates value
- The financing structure and repayment terms
- The risks involved
- Their own income, reserves, and financial capacity
- The possibility that historical performance may not continue in the future
Leverage requires maturity, patience, and preparation. The investor must be able to evaluate both the opportunity and the downside with clear judgment.
Leverage and Wealth Creation
Used prudently, leverage can help investors move from simply saving capital to controlling productive assets. However, leverage itself does not create wealth. The assets, the strategy, the cash flow, the economics, and the discipline behind the investment are what matter. Leverage only changes the structure through which capital is deployed.
The Golden Principle
Never let the excitement of controlling a larger asset make you forget that borrowed money remains an obligation.
The question should not simply be:
“How much can I borrow?”
It should be:
“How much risk can I responsibly carry while pursuing this investment opportunity?”
That second question reflects a more mature and disciplined approach to investing.
Final Thought
Investment leverage can be powerful, but power without knowledge can become dangerous. A financially educated investor does not use leverage simply because it is available. They use it selectively, understand the risks, protect their cash flow, and make decisions based on the economics of the investment rather than emotion. Leverage should be a servant of the investment strategy—not the strategy itself. The ultimate objective remains the same: build ownership, build productive assets, and build sustainable wealth.
Comments0
No comments yet. If something here landed, say so. It helps other readers know what to look at.