
Securing and Preserving Generational Wealth
Nine pillars for protecting wealth, preparing heirs, and leaving a legacy that outlives the wealth creator.

By Junah Mpofu
More than 33 years in banking, including mortgage and credit lending, and a real estate portfolio of her own
· Investing · Retirement
Read to the end to earn a 20 gold points reward.
What is the Gold Points Reward (GPR)?
GPR is our points reward system. As the Junahyeng Academy platform grows, it lets you earn points and rewards: the more points you earn, the higher the rewards you will unlock in due course.
You earn points for reading and engaging with our guides and articles. Soon you will also earn them for referring friends to the platform, engaging with our socials, and more.
Create a free account to keep the points you earn.
Building a Legacy That Can Outlive the Wealth Creator
Creating wealth is an achievement. Preserving it—and transferring it responsibly to future generations—is an entirely different responsibility.
Many people work their whole lives to accumulate wealth. Yet wealth can disappear surprisingly quickly when there is no structure, no plan, no financial education, and no clear understanding of its purpose.
Generational wealth should therefore not be viewed simply as money, property, investments, or businesses handed down to children. True generational wealth includes financial assets, knowledge, values, principles, relationships, and systems that enable the next generation to preserve and build upon what has been created.
The question is not simply, “How much wealth can I leave behind?”
A more important question is, “What structure, knowledge, values, and safeguards will I leave behind so that the wealth can continue to create value?”
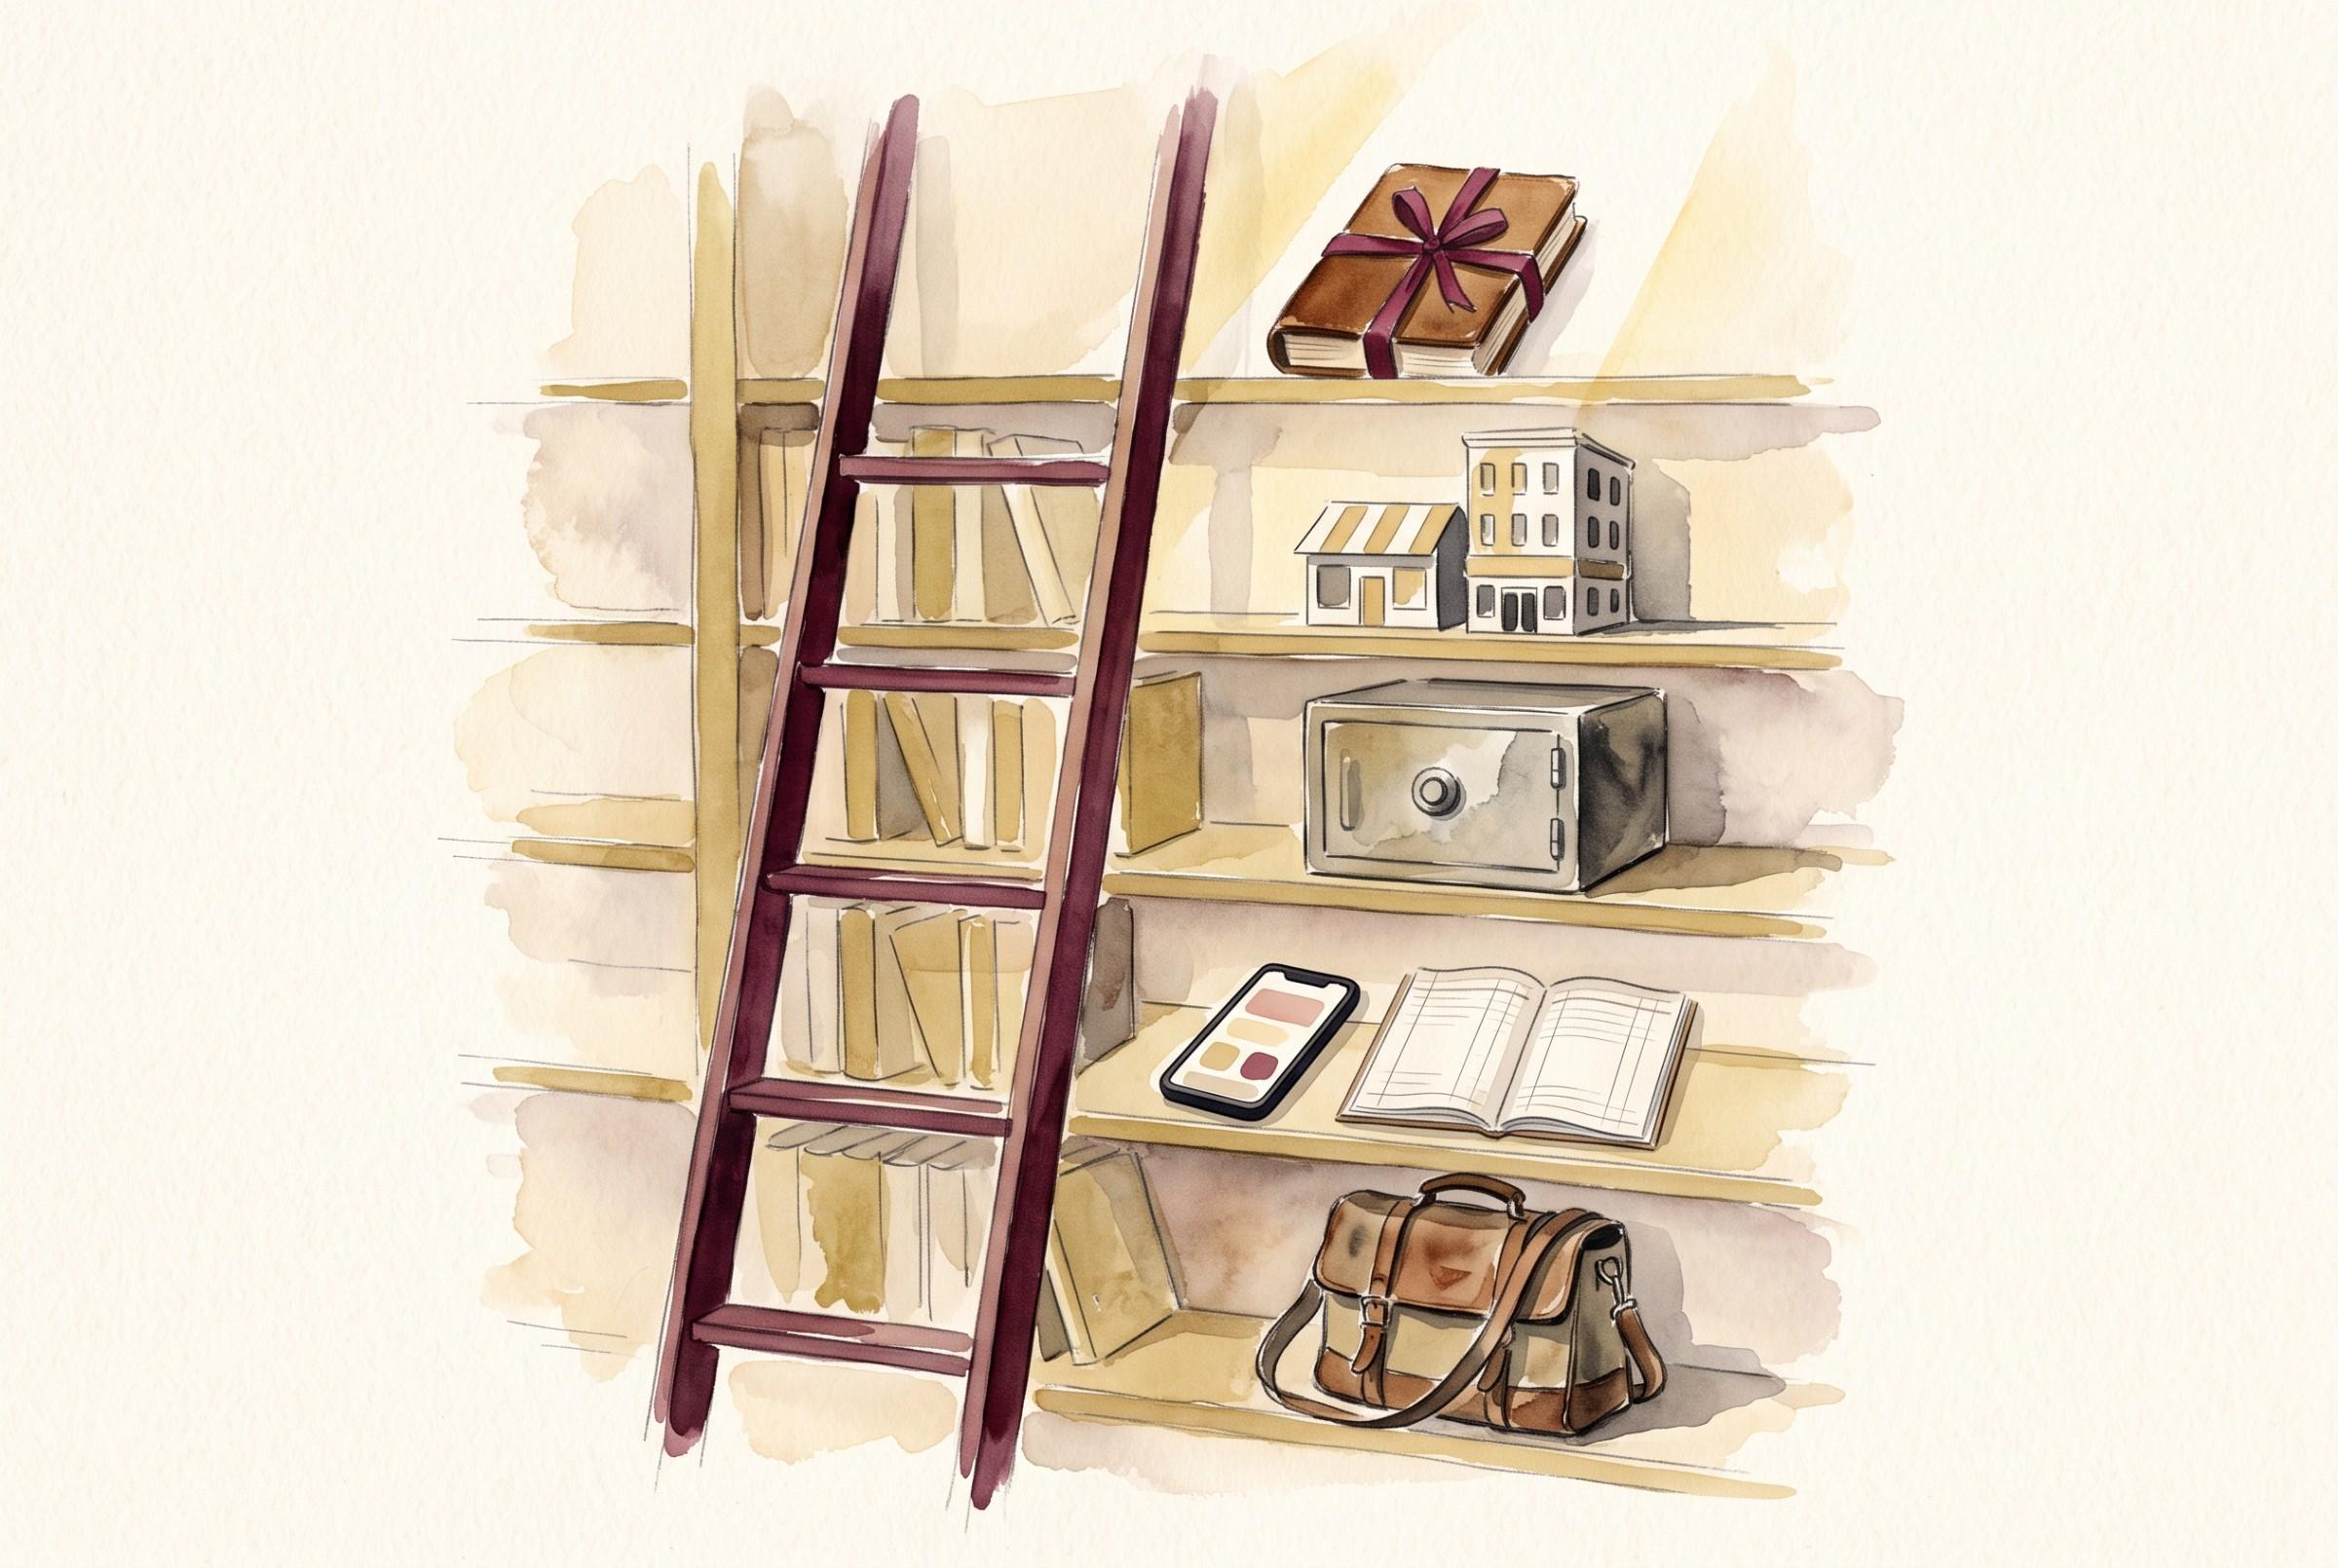
Here are nine important pillars for securing and preserving generational wealth.
1. Establish the Appropriate Legal Structure
Wealth should not be accumulated without considering how it will eventually be protected, managed, and transferred.
Depending on the nature and size of the estate, appropriate legal structures may include wills, trusts, business entities, beneficiary designations, powers of attorney, and other estate-planning arrangements.
The purpose is not simply to determine who receives what. Proper structure can help establish who controls assets, how assets are distributed, when beneficiaries receive them, and how the wealth creator’s wishes are carried out.
This is an area where qualified estate-planning attorneys and tax professionals should be consulted because laws differ by jurisdiction and individual circumstances.
Wealth without structure can become vulnerable.
2. Diversify and Eliminate “Dead Assets”
Preserving wealth requires periodically examining which assets are producing value and which are not contributing to growth, income, or long-term stability.
Some assets appreciate, generate income, or provide strategic benefits. Others consume money, time, maintenance, and attention without producing meaningful returns.
These can become what I call “dead assets.”
A family should periodically ask:
- Is this asset producing value?
- Is it appreciating?
- Does it generate income?
- Does it serve an important family purpose?
- What does it cost to maintain?
- Would the capital be more productive elsewhere?
Diversification is equally important. Concentrating too much wealth in one property, business, industry, or investment can expose a family to unnecessary risk.
The objective is not simply to own many things. It is to own a balanced collection of productive assets that can withstand changing economic conditions.
3. Establish Shared-Value Family Governance
One of the greatest threats to generational wealth is not always the economy. Sometimes, it is the lack of preparation within the family.
If heirs inherit wealth without understanding how it was created, they may know how to spend it without knowing how to preserve it.
Family governance can create a framework for discussing:
- Family financial values
- Responsibilities associated with wealth
- Expectations surrounding inherited assets
- Decision-making
- Business ownership
- Investment principles
- Philanthropy
- Education and preparation of heirs
Where appropriate, families can establish regular family meetings or other formal processes for communicating these principles.
The goal is not to control every decision of the next generation. It is to prepare them to become responsible stewards.
Educating heirs
Financial education should begin long before wealth is transferred.
Children and future heirs should learn the difference between income and wealth, assets and liabilities, consumption and investment, wants and needs, and ownership and stewardship.
An inheritance should not become a substitute for financial wisdom.
4. Record Your Personal Ethics, Values, and Purpose
One of the most overlooked components of legacy planning is the story behind the wealth.
Numbers can tell future generations what was accumulated. They cannot necessarily tell them why.
Consider documenting the principles that guided your financial journey:
- Why did you work so hard?
- What sacrifices were made?
- What values influenced your decisions?
- What did money mean to you?
- What causes were important to you?
- What mistakes did you make?
- What lessons did you learn?
- What do you hope future generations will do with what they inherit?
- This can become a personal legacy letter, family mission statement, or statement of values and purpose.
- The greatest inheritance may not always be the financial statement. Sometimes, it is the wisdom written beside it.
5. Maximize Capital Growth and Manage Capital Gains Wisely
Preservation does not mean keeping wealth stagnant. Capital should continue to work.
Investments should be reviewed with consideration for long-term growth, income generation, risk, liquidity, and applicable tax consequences.
Capital gains should also be managed strategically and legally. The objective is not simply to avoid taxes; it is to understand the tax consequences of investment decisions and use legitimate planning opportunities appropriately.
Because tax laws are complex and change over time, significant decisions should be reviewed with qualified tax and financial professionals.
The goal is to maximize after-tax wealth—not simply gross wealth.
6. Make Risk Management an Ongoing Practice
A wealth-preservation plan should never be considered permanently finished.
Life changes. Markets change. Tax laws change. Businesses change. Family circumstances change.
Therefore, risk management should become an ongoing practice rather than a one-time exercise.
Periodic reviews should consider areas such as:
- Insurance coverage
- Investment concentration
- Business risks
- Property exposure
- Liability protection
- Estate documents
- Beneficiary designations
- Liquidity needs
- Changes in family circumstances
- Changes in tax and estate laws
- A plan that was appropriate five or ten years ago may no longer be appropriate today. Preservation requires vigilance.
7. Establish a Tax-Efficient Giving and Stewardship Strategy
Wealth can become more meaningful when it extends beyond the family.
For families who have accumulated significant resources, charitable giving can become part of a broader stewardship strategy.
This may include supporting:
- Children and families in need
- Educational opportunities
- Community organizations
- Religious or charitable institutions
- Health and humanitarian causes
- Programs that empower disadvantaged individuals
There may also be legitimate tax-efficient ways to structure charitable giving, depending on the individual’s circumstances and applicable law.
However, the motivation should go beyond obtaining a tax benefit. Tax planning can increase the efficiency of giving, but stewardship gives the giving its purpose.
The question becomes, “How can the wealth entrusted to me continue to create good beyond my immediate family?”
8. Engage Qualified Professional Wealth Management Services
As wealth becomes more complex, managing everything alone may become increasingly difficult.
A family may need the coordinated services of professionals such as:
- Financial planners
- Investment professionals
- Estate-planning attorneys
- Tax professionals
- Insurance professionals
- Business advisers
- Accountants
The purpose of professional advice should not be to surrender responsibility. It should be to increase informed decision-making.
The wealth owner remains the decision-maker while qualified professionals provide specialized knowledge.
Professional advice is particularly valuable when different areas of wealth management intersect—investments, taxes, estate planning, business ownership, insurance, and charitable giving.
9. Seek Fiduciary Oversight
Finally, families should understand the importance of fiduciary responsibility.
A fiduciary is generally obligated to act in the client’s or beneficiary’s best interests, subject to the specific legal and professional relationship involved.
This distinction matters because not every financial professional operates under the same legal standard in every service relationship.
Families should therefore ask potential advisers: “Are you acting as a fiduciary for me, and in which services and circumstances?”
Understanding how an adviser is compensated, what conflicts of interest may exist, and what fiduciary obligations apply can help families make better-informed decisions.
An independent fiduciary or appropriately structured oversight arrangement can also provide an additional layer of accountability.
The Real Meaning of Generational Wealth
Ultimately, generational wealth is not merely about transferring possessions from one generation to another. It is about transferring capacity.
The first generation may create the wealth. The second generation must learn to manage it. The third generation must understand why it exists. And every generation must have the wisdom to preserve, grow, and use it responsibly.
Therefore, the strongest legacy may consist of five things:
- Assets to provide resources.
- Knowledge to provide understanding.
- Values to provide direction.
- Structures to provide protection.
- Purpose to provide meaning.
Without these, an inheritance can become a temporary advantage. With them, wealth can become a generational platform for opportunity, stability, service, and positive impact.
Closing Thought
We spend much of our lives learning how to make money. We should also learn how to protect it, preserve it, multiply it, and give it meaning.
The true measure of financial success may not be the size of the estate we leave behind. It may be whether the people who come after us are equipped to use what we built wisely.
Generational wealth is therefore not simply what we leave for our descendants. It is what we teach them to do with what we leave behind.
A Legacy Worth Leaving
Build the wealth. Protect the wealth. Teach the next generation. Give the wealth purpose. And leave behind more than money—leave behind wisdom.
About the Author: Junah Mpofu believes knowledge should empower people to make better financial and life decisions. Drawing on decades of experience in banking, education, and leadership, she writes to simplify complex ideas and encourage readers to create lasting wealth, wisdom, and purpose.
Legal Disclaimer This blog offers educational insights and institutional frameworks only. It does not provide personalized, regulated investment, tax, or legal advice. Readers should consult qualified professionals before making decisions based on their individual circumstances.
Comments0
No comments yet. If something here landed, say so. It helps other readers know what to look at.